PRICING

Plan Pricing

Pricing is an affordable $500 annual base fee + $20 per participant per year. There are no other employer fees.

Pricing
Plan Types
Administration
Profit Sharing With Classes

NEW 401k

Employer Administration Fees

one-time install fee:

$250

annual fee:

$500

+ $20 per

participant

Employee INTERNAL Expense

Annualized program fee total:

.80%

THIS PLAN IS RIGHT FOR YOU IF:

you are starting a new 401k
you would like an open-universe of funds & ETFs
you have 1 to 500 employees

EXISTING 401k

Employer Administration Fees

one-time install fee:

$250

annual fee:

$500

+ $20 per

participant

Employee INTERNAL Expense

Annualized program fee total:

.80%

THIS PLAN IS RIGHT FOR YOU IF:

you have an existing 401k, or
you have 501+ eligible employees, or
you would like an open-universe of funds & ETFs & the option fora self-directed brokerage account

*custom-quoted, discounted based on plan size
Plan Types

Safe Harbor 401k Vs. Traditional 401k

Which one is better?
It depends on the design that best satisfies the priorities of your business. For all businesses, the IRS permits a selection of one of (2) types. Certain requirements apply to each, to meet qualification rules for ongoing tax benefits.
A Safe Harbor 401k and Traditional 401k each permit the same contribution limits by employees; however, there are specific rules and features regarding employer contributions and testing that differentiate the plan types. Our team will detail these plan elements to help you with the best fit before implementation. We also stay connected after your plan is in place to assure that the original blueprint is current with your dynamic business developments and benefit intentions.
SAFE HARBOR 401k
any business size with 2+ eligible persons
eligible employees may make pre-tax or Roth elective deferrals through payroll deductions
owners(s) & Highly Compensated Employees can save up to IRS maximum, annually
employer mandatory contribution from (4) options annually. minimum match is 3.5%
no ADP testing, no ACP testing, and no Top Heavy testing
Top Heavy testing applies as a ratio of total plan assets by owners &key employees
flexible Profit Sharing contributions up to 25% of pay, with highest amount to owner(s)
eligibility can be up to age 21 and waiting period maximum of 1 year of full-time service
rollovers to & from other retirement accounts
loans & hardship withdrawals permitted
TRADITIONAL 401k
any business size with 2+ eligible persons
eligible employees may make pre-tax or Roth elective deferralsthrough payroll deductions
owners(s) & HCE(s) typically cannot save up to IRS maximum,
annually
employer is not required to make contributions,
they are flexible
ADP testing applies, limiting saving % for owner(s) & HCE(s)
Top Heavy testing applies as a ratio of total plan assets by owners &key employees
flexible Profit Sharing contributions up to 25% of pay, with highest amount to owner(s)
eligibility can be up to age 21 and waiting period maximum of 1 year of full-time service
rollovers to & from other retirement accounts
loans & hardship withdrawals permitted
A business is also permitted to amend from one plan type to another, from year-to-year, as long as the specific IRS deadlines are adhered to, and employee notices are provided.
Source of data: IRS.gov

Administration

USA 401k is a full-service provider that offers a “bundled”program to make things easiest on you, the employer.
Full-Service Provider
USA 401k Features
Employer Services
Payroll Integration

Full-Service Provider

USA 401k is a full-service provider that offers a “bundled” program tomake things easiest on you, the employer.
Most small & mid-sized 401k programs are administered by a third partyknown as a TPA, where they are unbundled and thus have more partiesinvolved, not all in one place.
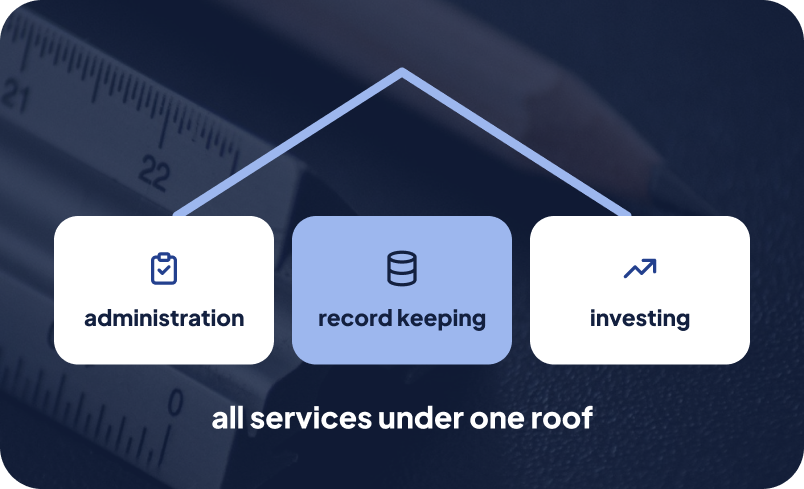
This program, as a package, neatly and efficiently coordinates allservices under one roof - administration, record keeping and investingtogether! So, you can rely on us to take care of managing your plan,leaving you more time to run your business.

USA 401k Features

Monthly Fee:

$0

Profit Sharing included,

$0

Signature-ready 5500 & all required disclosure notices included

Businesses 1 – 1,000 employees

Total annual employer administrationfee: $500 + $20 per participant

Full payroll integration & contribution processing!

Prevailing wage employees, including fringe benefit payments, are fully accommodated

Loans, hardship withdrawals,participant tax reporting built-in

Roth 401k included

Profit Sharing included, $0

Monthly Fee: $0

Employee Card One

Your administrator provides concierge-level guidance throughoutyour installation and then ongoing to keep your 401k on track.
service excellence, responsiveness from your administration team
payroll integration for seamless contribution processing through your existing payroll system
Tax form 5500 included, $0
Profit Sharing included, $0
loans, hardship withdrawals, distributions, rollovers
compliance under DOL, year-end testing, all tax reporting
flexible design - plan document customized to your specific interests
employee education meetings, no limit, $0

Employee Support

Mobile enrollment
Expert on-site enrollment meetings, seminars for retirement readiness
1-on-1 financial reviews & investment guidance
Comprehensive enrollment materials, 401k benefits, Traditionalvs. Roth 401k
Customer service # & account manager concierge service
Retirement income calculators, portfolio allocation models
Morningstar® reports
Statements updated daily online, lifetime total returns
Loan modeling
Learn About Employee Education

Payroll Integration

USA 401k includes 360 degree payroll integration for seamless contribution processing through your existing payroll system!
Vestwell, the exclusive record keeper and administrator, has themost modern technology in place for full payroll sync. This connectivity to leading providers, known as 360 degree payroll integration, allows key elements like 401k contribution processing and census data collection to be processed securely and automatically through direct feeds. The end result is a better experience and hands-off for you as the busy employer.

Automated payroll contribution processing removes employer accounting and reduces liability. This is included at no extra cost.

360 Degree Available for the following providers:

Payroll Connections Among The Nations Largest!
ADP Workforce Now
ADP Total Source
Automatic Business Computing
Balance point
Coastal
Commonwealth
CorePay
Encompass
ePay
Gusto
Insperity
iSolved
Namely
OnPay
Paychex Flex
Paycom
Paylocity
Paycor
PayDay
PayPro
PayServ
Premier Now
Premier Payroll
Press Gold
QuickBooks By Intuit
Rippling
Run
Solex
The Payroll Network
Thread
Thrive
Toast
UltiPro
Vision
Zuma

If You Don’t See Your Payroll Provider ListedNot to worry. Even without a direct connection, USA 401k’s record keeper will process your payroll through Vestwell’s next-gen enginewith real time data.

Profit Sharing
With Classes

New Comparability is a type of Profit Sharing plan thatmaximizes the amount contributed to a target group ofparticipants, typically owner(s), officers or keyexecutives.

With a New Comparability Profit Sharing plan, employees are divided into groups, each receiving a contribution that is a different percentage of their compensation. One common arrangement is to include owners and officers in group “A,” management in group “B,” and clerical/staff in group “C.”

owners and officers
management
clerical/staff

At the same time, this design minimizes the total cost of the company’s contributions on behalf of its other employees. A New Comparability Profit Sharing plan permits disparity of contributions, allowing different allocations among separate groups of plan participants. Contributions can be allocated to employees based on several different methods (or by a combination of these):

based on owner status
based on officer,executive, or highercompensation status

This special type of Profit Sharing plan design offers a great deal offlexibility in the total contribution amount (for years that one is made),of up to 25% of eligible pay for owners and officers or key executivesand lower percentages for other named classes of employees. Also the employer may skip the contribution entirely in any years when aProfit Sharing arrangement is not intended.
This retirement plan can be custom-designed, initially, allowing:

groups to be determined by title, salary, service, or position (or even a combination of these categories)
the owners and officers or key executives to receive a larger allocation (as a percentage of pay) than other Plan participants
the owner and officers or key executives toreceive a maximum allocation of up to themaximum benefit limit allowed underSection 415 of the Internal Revenue Code.

Typically, the Board of Trustees (or a business owner, plan Administrator, or other individual acting on behalf of a Board of Trustees) will make thedetermination as to the specific division of employee classifications. The Administrator can assist with general rules governing the process of assigningclassifications.
Maximums For An Owner, Officer, OrKey Executive
Maximum contributions to reward key participants depend upon your specific census, including the ages and compensation level of all employees. To receive an illustration of estimated contributions, simply provide a census including intended named employee classifications (i.e. A,B,C).
There is an overall limit that can be contributed between employer and employee, known as the 415 limitation. That maximum includes employee deferrals, matching, and Profit Sharing. Your Administrator will show maximum allocations per participant, where you have flexibility to contribute at a lesser scale. The limits differ for sole proprietors and partnerships since special IRS calculations apply.
Flexibility In Design
There is considerable flexibility in the design of New Comparability Profit Sharing plans. This type of plan is tested for nondiscrimination on a cross- tested basis, under Section 401(a) (4) of the Internal Revenue Code. An actuarial consultant (provided through your Administration team) will help in determining the right plan design, based on your specific interests. Each plan is customized according to many factors, including:

Who is the plan intended to benefit?

Will the owner, officers, or key executives be receiving maximums?

How many classes of employees and who is in eachclass?

* New Comparability Can Be Used WithA 401k Plan
A New Comparability Profit Sharing plan pairs well with a 401k and isincluded without cost in USA 401k! For an existing 401k plan, this element can be added as a plan enhancement by amendment. NewComparability Profit Sharing works especially well for 401k plans whereowners and officers or key executives are currently limited under ADP(average deferral percentage) testing. When owners and officers or keyexecutives are not reaching their desired savings level under the 401k byitself, this is perhaps a signal to consider an alternate design. The additionof a New Comparability Profit Sharing plan often permits these highlycompensated employees to achieve their desired level of overallretirement capital accumulation.